

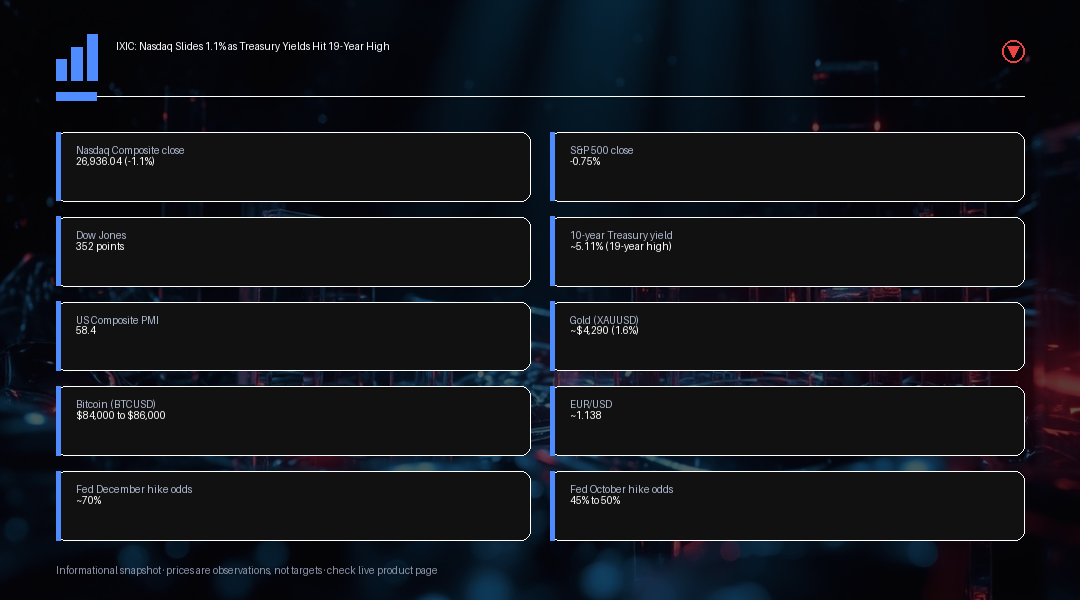
IXIC: Nasdaq Slides 1.1% as Treasury Yields Hit 19-Year High The Nasdaq Composite fell 1.1% on Wednesday, September 23, 2026, closing at 26,936.04 and retreating after two consecutive record closes, as stronger-than-expected US economic data revived rate-hike concerns and sent Treasury yields to their highest level in nearly two decades. The selloff was broad-based. The S&P 500 lost about 0.75%, the Dow Jones Industrial Average shed roughly 352 points, and the Russell 2000 underperformed the larger indices as smaller, more rate-sensitive companies absorbed the greatest pressure. The catalyst was a stronger-than-expected reading on US growth: the S&P Global flash composite PMI climbed to 58.4 in September, its highest level since July 2021, signaling faster economic activity but also renewed inflationary pressure. In response, the 10-year Treasury yield surged to close near 5.11%, with an intraday high approaching 5.14%, marking its highest level since 2007. That yield surge reshaped Fed expectations. Markets were pricing roughly a 45% to 50% chance of an October rate increase, alongside a substantially higher probability, near 70%, of at least one more Fed hike by December 2026. That distinction matters: the market has grown considerably more confident that another hike arrives before year-end even though conviction around an immediate October move remains closer to a coin flip. Early Thursday trading offered little relief, with Nasdaq 100 and Dow futures down roughly 0.1% as investors awaited a high-profile meeting between President Trump and President Xi Jinping in Washington. An extension of the US-China trade truce was expected to top the agenda, alongside discussions on artificial-intelligence export restrictions, semiconductor supply chains and Taiwan, all of which carry direct implications for chipmakers and other technology companies with meaningful exposure to China. Asian markets were mixed heading into the summit rather than staging a broad rally. Japan's market was closed for a holiday, mainland China and Hong Kong both declined, and Australia edged only modestly higher, underscoring that Wednesday's Wall Street selloff was not being uniformly shrugged off across the region. Cross-asset moves told a consistent story about higher-for-longer yields reshaping positioning. Brent crude held around $104 per barrel amid ongoing Middle East tensions tied to the Strait of Hormuz, adding a fresh source of inflation concern on top of the stronger PMI data. The US dollar pushed toward a two-month high, with EUR/USD falling to around 1.138, near its lowest levels in roughly two months. Gold dropped about 1.6% to near $4,290 an ounce despite the equity selloff, a move explained by the fact that bullion pays no income and becomes comparatively less attractive as Treasury yields rise, with a firmer dollar adding a second headwind by making gold more expensive for buyers outside the US. Bitcoin eased toward the $84,000 to $86,000 range after briefly touching near $87,400, its highest level since January, leaving the former $82,000 resistance area as an important support test going forward. The Trump-Xi summit adds a further layer of event risk on top of the yield-driven selloff, since any surprise on tariff levels, technology-export controls or the length of the newly extended trade truce could move chip-sensitive names sharply in either direction regardless of what Treasury yields do next. Markets have generally treated the prospect of a truce extension as a mild positive, but traders should be cautious about assuming a smooth outcome given how quickly prior US-China negotiations have shifted tone. Meanwhile, the divergence between Meta's gain and the broader Nasdaq's decline is a useful reminder that Wednesday's selloff was concentrated in yield-sensitive growth names rather than reflecting uniform weakness across every corner of technology, and stock-specific catalysts, such as Meta's Muse-driven momentum, can still outweigh macro headwinds on a given day. Costco's print on Thursday will offer one of the clearer near-term reads on whether elevated borrowing costs are beginning to filter through to household spending, which in turn will help traders judge how much further the current rate-driven repricing in equities still has to run. Individual names diverged from the broader tape. Meta gained about 1% on continued enthusiasm for its Muse artificial-intelligence assistant even as the wider technology sector fell, while Alphabet and Amazon were among the names weighing on the index. Attention now turns to Costco, which reports earnings after Thursday's closing bell; consensus estimates point to earnings near $6.55 per share on roughly $94.9 billion in revenue, a release that should offer traders a fresh read on whether consumer spending can hold up under a still-elevated rate environment. That report will be watched closely for any sign that the elevated rate backdrop is beginning to crimp big-ticket household spending, a signal that would carry read-through for the broader consumer and retail sectors heading into the final quarter of the year.
Trading Insight
The central question for equity traders is whether Wednesday's decline represents routine profit-taking after two record closes or the start of a more sustained valuation reset driven by higher bond yields, and the 10-year yield's push toward 5.11%, with intraday highs near 5.14%, is the level to watch for an answer. A further move higher in yields toward that zone would likely keep pressure on rate-sensitive growth names, while a pullback from these multi-year highs would be a signal that equities can stabilize even with a firmer Fed outlook priced in. Near-term catalysts include the outcome of the Trump-Xi summit, which carries direct read-through for chipmakers and other China-exposed technology names, and Thursday's Costco earnings, which will help confirm whether consumer spending remains resilient enough to tolerate a still-elevated rate backdrop. The simultaneous pullback in gold and Bitcoin alongside dollar strength reflects a classic yield-driven, risk-repricing dynamic rather than a broad flight from risk assets, so traders should watch Treasury yields and the dollar index together as the primary cross-asset confirmation signal. A retreat in yields from current cycle highs, combined with a benign Trump-Xi outcome, would be the clearest combination of catalysts that could support a near-term stabilization in the Nasdaq and broader technology names.