

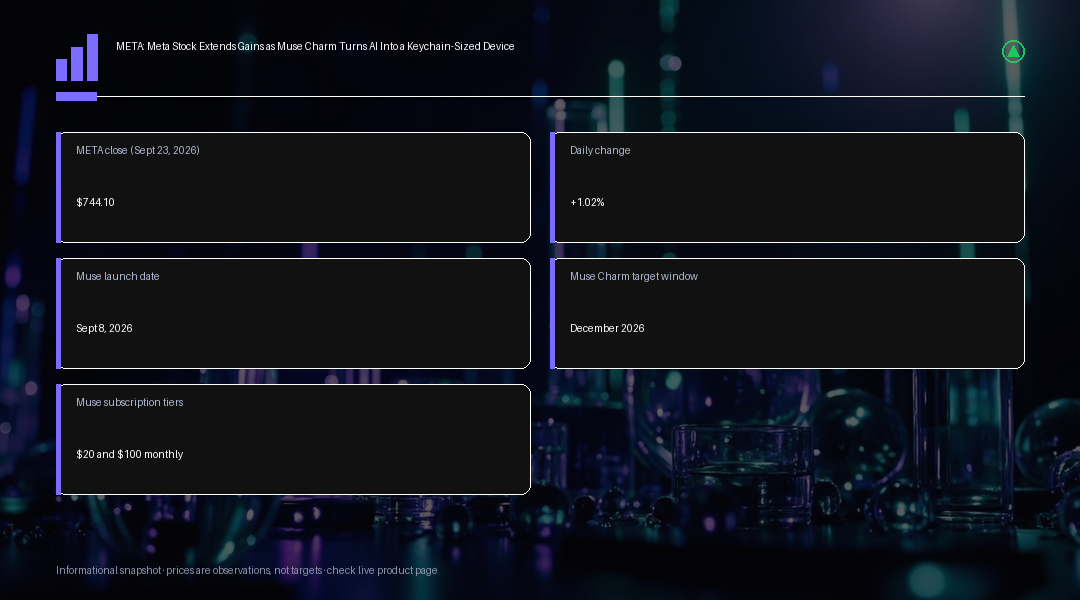
META: Meta Stock Extends Gains as Muse Charm Turns AI Into a Keychain-Sized Device Meta Platforms closed at $744.10 on Wednesday, September 23, 2026, up about 1.02% even as the broader Nasdaq fell sharply, as investors continued to reward the company's push to turn its Muse artificial intelligence assistant into a physical, everyday product rather than just another app. Muse itself launched in the United States on September 8, 2026, reaching users through iOS, Android, the web at muse.ai, and WhatsApp. The assistant can send emails, book travel, organize finances, order goods and complete other multistep tasks on a user's behalf. Meta is offering a free tier alongside $20 and $100 monthly subscription plans aimed at heavier users, and the initial rollout has so far been limited to the US market. At Meta Connect 2026, chief executive Mark Zuckerberg went a step further and unveiled Muse Charm, a small, keychain-sized companion device carrying a fingerprint sensor and a compact display that shows the Muse avatar, along with real-time voice interaction. The device is designed to let users reach Muse without opening a phone app or wearing a separate pair of smart glasses. Importantly, the Charm was shown as a prototype rather than a shipping product: Meta said it aims to bring the device to market around the December 2026 holiday period, but no price has been announced and the hardware was not yet ready to ship at the time of the demonstration. Commerce is emerging as a second pillar of the Muse story alongside the subscription model. Shopify has enabled agentic checkout through its Shop Pay system across its merchant network, and PayPal has announced support for Muse-driven checkout across its own base of merchants, giving the assistant a growing set of rails to complete purchases directly. Amazon, by contrast, has blocked Muse from shopping on its platform, a decision that underscores how unevenly retailers are responding to AI agents that can browse and buy on a shopper's behalf. The commerce integrations point toward a future monetization opportunity for Meta beyond subscription revenue, although the company has not publicly confirmed a specific transaction-fee model, and investors should treat that as a developing storyline rather than a locked-in revenue stream. Meta's stock has risen sharply since the Muse launch on September 8, and the company's market value has grown by hundreds of billions of dollars over that stretch as investors reassess years of heavy artificial-intelligence spending against tangible evidence of a consumer product taking shape. Wednesday's 1% gain, arriving on a day when technology stocks broadly sold off on the back of surging Treasury yields, is itself notable: it suggests that Meta's Muse-driven narrative is currently strong enough to offset some of the macro pressure weighing on the wider Nasdaq. The broader competitive context also matters for how investors should read Wednesday's move. Meta is not the only large technology company racing to embed an AI assistant into daily life, but the decision to pair Muse with a dedicated physical device sets it apart from rivals that have so far kept their assistants confined to phone apps or browser tabs. That hardware bet carries real execution risk, since consumer electronics launches routinely slip on timing or arrive with pricing that dampens initial demand, and Meta has offered no price point for the Charm device at this stage. At the same time, the commerce partnerships already in place with Shopify and PayPal give Meta a tested distribution channel it can lean on regardless of how quickly the standalone hardware business matures, which helps explain why investors are willing to look past the unanswered pricing and shipping questions for now. Amazon's decision to block Muse from its shopping platform is also worth watching closely in the coming months, since it signals that at least one major retail gatekeeper views agentic shopping assistants as a competitive threat rather than a feature to embrace, a dynamic that could shape how quickly agentic commerce scales across the wider retail sector. The bigger picture for investors is that Meta appears to be building toward a genuine consumer hardware and commerce platform rather than simply pouring more capital into data centers with an uncertain payoff timeline. That shift in narrative, if it continues to be validated by product execution, gives the market a more concrete reason to look past near-term AI capital-expenditure concerns. The risks run in the opposite direction as well. The Charm remains unshipped, its price is unknown, and a slip in the December timeline or a lukewarm consumer reception could quickly undercut the current enthusiasm. Competitive friction, illustrated by Amazon's decision to block Muse from its shopping platform, is also a reminder that Meta's ambitions to sit between consumers and merchants will not go unchallenged by other large platforms with their own commerce interests to protect.
Trading Insight
For traders positioning around Meta shares, the key distinction to hold onto is between what has already shipped and what is still a prototype. Muse itself is live and monetizing today through its subscription tiers and expanding merchant partnerships, while Muse Charm remains an unpriced device targeted for a December holiday launch, which means the stock's near-term path depends heavily on execution risk rather than confirmed revenue. Watch for concrete pricing and shipping-date confirmation on the Charm device as the next catalyst, along with any disclosure on how Meta intends to monetize agentic commerce transactions, since that remains unconfirmed and could move the stock meaningfully in either direction once clarified. Meta's ability to keep rising even as the broader Nasdaq fell on rate concerns is a sign of idiosyncratic strength, but it also means the shares could be more exposed than the index if the Muse narrative stalls or if a competing platform matches Meta's hardware ambitions. Cross-referencing Meta's move against broader technology-sector price action, and against how retail partners like Shopify and PayPal report agentic commerce volumes over the coming quarters, should help traders judge whether the current premium in the stock is being justified by real usage growth or is running ahead of confirmed fundamentals.